Reviewing one home
Use 100% ownership and debt allocation to understand the simple gap between value and secured debt. A sale estimate would need separate selling costs, tax and settlement adjustments.
Home equity is the difference between a property's estimated value and the debt secured against it. It is a simple snapshot, not the amount you can necessarily borrow or receive after a sale.
Inputs stay in this browser tab and clear on reload. Download if you want to keep a copy.
User-entered estimate in AUD. No sale costs, tax, borrowing eligibility or state-specific rules are calculated. General information, not personal financial, tax or legal advice.
Follow the tool, step by step
Choose a guide below. Follow the labelled screenshot, then try it with your own information.
Step 1 of 3
Enter a current estimated value and the total debt secured against that property. Check for additional secured facilities. This calculator does not obtain a bank valuation or look up a loan balance.
Try this in the tool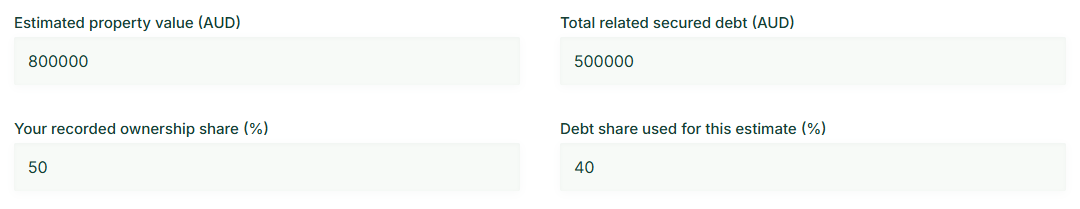
Step 2 of 3
Use 100% in both fields for the whole-property view. For an allocated estimate, enter your recorded ownership share and the debt percentage you intend to use. These percentages describe your calculation, not the legal limits of a borrower’s liability.
Try this in the tool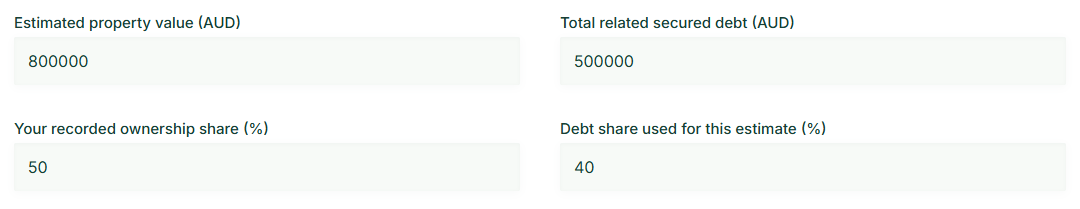
Step 3 of 3
Calculate home equity to see gross equity, your allocated estimate and the whole-property loan-to-value ratio. Download the inputs and results together. Use Clear figures to start another property.
Try this in the tool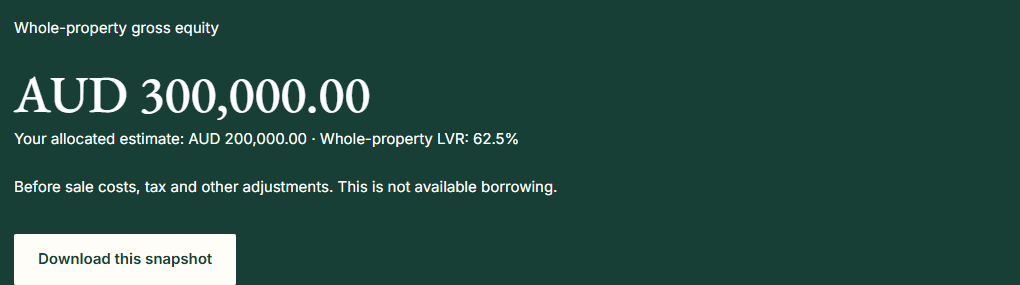
Worked example
The whole property has A$300,000 gross equity. The allocated estimate is A$400,000 (50% of its value) less A$200,000 (40% of its debt). The whole-property LVR is 62.5%. Different percentages should have a clear reason and should be checked against the relevant records.
Follow the inputs
Value less related debt
 Property valuationOwnership and policy
Take the next step with Financial Portfolio
Bring the property, its related loan, recorded owners and insurance information together in Financial Portfolio. Attach the source documents you use and update the recorded figures when circumstances change, so you can revisit the context behind the calculation.
App access is currently through the waitlist. Keep your download for reference. Tool entries are not sent to the app or imported automatically.
Enter a current property estimate and the related loan balance. If this is one owner's share, identify the ownership percentage and keep the treatment of debt consistent. For example, an A$800,000 property with an A$500,000 related mortgage has A$300,000 in simple gross equity before transaction costs and other adjustments. The result can be negative.
Sale costs, tax, other secured debts, lender policy, valuation differences and legal ownership details may change the practical outcome. A home-equity number does not indicate borrowing eligibility. For a broader picture, put the property and mortgage beside your other records in the asset records and liability records. Moneysmart defines equity in its home-equity release guide; that guide is about a specific borrowing context, not this calculator's result.
The tool runs in this browser tab. Your inputs are not sent to Financial Portfolio, stored in a user account or passed through the signup link. A reload clears the working state. Download a CSV if you want a copy, and keep it somewhere appropriate for the information it contains.
Financial Portfolio can help you maintain related records, but this public result does not create a portfolio or verify a source document. Read the privacy policy and terms of use, or visit the Help Center for product questions.
Put the result to work
Use 100% ownership and debt allocation to understand the simple gap between value and secured debt. A sale estimate would need separate selling costs, tax and settlement adjustments.
Calculate each property separately, naming and dating each downloaded file. Financial Portfolio can connect those property records to their loans and owners so one household total does not hide which debt relates to which home.
Subtract the outstanding debt associated with the property from its estimated current value. Check whether other secured debt should be included for your purpose.
No. The simple figure omits selling costs, tax and other adjustments.
Calculate each property separately, then keep owners, loans, values and documents connected in a structured property record.
From a useful start to connected records
Explore how Financial Portfolio connects the assets, debts, people and paperwork you maintain.